

Blogs
PW Consulting Projects 9.5% CAGR for High Speed Oven Market to Hit $7.88B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the High Speed Oven Market: Navigating the 2026–2032 Growth Cycle
The commercial foodservice sector is undergoing a profound operational transformation, driven by acute labor constraints, rising real estate costs, and an unprecedented demand for rapid ticket-to-order fulfillment. In this volatile environment, the high speed oven market has emerged as a critical enabler of kitchen efficiency, bridging the gap between traditional cooking methodologies and the aggressive throughput requirements of modern quick-service and fast-casual operations. As we analyze the trajectory of this sector through 2032, our latest market research provides a comprehensive strategic blueprint for manufacturers, investors, and foodservice operators aiming to capitalize on a projected industry expansion. This article outlines the macro-economic foundations of the sector, highlights the competitive dynamics shaping vendor strategies, and details the actionable intelligence embedded within our full report.
The Macro Trajectory: A High-Growth Window Across 2026–2032
Market data spanning the evaluation period paints a clear picture of sustained acceleration. Following a robust historical baseline, the industry has entered a steep growth phase, with the overall market value reaching $4,370.0 million in 2025 before projected to chart $4,686.06 million in 2026. Our forecast models indicate that this momentum will compound consistently, pushing revenue toward $7,880.0 million by 2032. This represents a compound annual growth rate of 9.5 percent, a figure that significantly outpaces broader commercial kitchen equipment benchmarks and underscores a structural shift in how operators are designing their culinary workflows.
The valuation trajectory does not merely reflect cyclical demand; it signals a permanent reorientation of commercial cooking infrastructure. As high-throughput concepts proliferate and legacy kitchen footprints contract, speed cooking appliances are transitioning from supplementary tools to central production assets. Organizations that align their capital expenditure strategies with this growth pattern stand to secure meaningful first-mover advantages in supply chain positioning, channel partnerships, and menu innovation capabilities.
Market Structure and Demand Drivers Shifting the Landscape
Segmentation Dynamics and End-Use Priorities
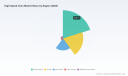
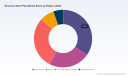
The current market architecture reveals a balanced but rapidly evolving distribution of demand across equipment configurations and deployment environments. Operators are increasingly evaluating built-in installation formats against standalone countertop solutions, with the strategic choice heavily dependent on modular kitchen design, ventilation constraints, and throughput targets. Simultaneously, end-use applications are bifurcating between high-volume restaurant environments and a diverse array of other commercial deployments, including corporate cafeterias, educational dining facilities, retail food halls, and airport concessions. This diversification is critical, as it insulates the market from overreliance on a single dining segment and broadens the addressable customer base for manufacturers and distributors.
Geographic Expansion and Infrastructure Maturation
Regional adoption patterns are stabilizing around established commercial foodservice hubs while demonstrating clear upward pressure in emerging markets. North American and European territories continue to anchor substantial share, anchored by mature restaurant supply chains, stringent health and safety compliance frameworks, and widespread adoption of ventless and impingement cooking technologies. Meanwhile, Asia Pacific and Latin American markets are exhibiting accelerating deployment rates as quick-service brands expand internationally and local operators prioritize operational efficiency to offset rising commodity and labor costs. Middle Eastern and African regions, though smaller in absolute valuation, are carving out niche growth corridors driven by hospitality infrastructure projects and tourism-centric foodservice concepts.
Regulatory Compliance and Operational Cost Pressures
The commercial deployment of high speed ovens is strictly governed by a multi-layered certification ecosystem. Equipment destined for U.S. and Canadian commercial kitchens must satisfy UL and NSF safety and sanitation standards, while ETL certification remains mandatory for market entry across North America. Ventless configurations introduce an additional compliance layer, requiring catalytic converter certification to meet stringent emissions thresholds. Furthermore, energy efficiency frameworks, including Energy STAR and related efficiency certifications, are increasingly influencing procurement decisions, particularly for models that integrate convection, microwave, and broil capabilities in a single footprint.
Worldwide Build-in High Speed Oven Market
Beyond regulatory overhead, labor economics are the most potent demand catalyst in the current cycle. High speed ovens routinely deliver cook times up to 80 percent faster than conventional equipment, directly compressing staffing requirements and reducing dependency on highly specialized culinary labor. In an environment where wage inflation and recruitment volatility remain unresolved, this labor efficiency premium is no longer a convenience feature—it is a financial imperative that dictates capital allocation and menu engineering strategies.
High Speed Oven Market
Competitive Arena: Strategic Moves and Product Evolution
Market concentration remains firmly consolidated, with the top three participants commanding a combined 62 percent share and the top five firms extending that footprint to 65 percent. This structure rewards scale, technical differentiation, and robust service networks, while simultaneously raising the barrier for new entrants attempting to disrupt established channel relationships.
Several active manufacturers are currently defining the competitive tempo through targeted product evolution and strategic positioning. Prática Klimaquip, operating out of Minas Gerais, Brazil, has solidified its footprint in commercial rapid-cook applications with stackable configurations such as the FIT XL and Rocket Express, specifically engineered for pizza, wing, and quick-service workflows. The Middleby Corporation, leveraging its TurboChef Technologies subsidiary based in Elgin, Illinois, continues to deploy impingement-based rapid-cook architecture optimized for high-volume foodservice throughput. Hatco Corporation, through its Ovention Ovens brand in Milwaukee, Wisconsin, maintains a strong emphasis on 100 percent ventless impingement systems that integrate seamlessly into constrained kitchen footprints without extensive exhaust infrastructure.
Merrychef Ltd., headquartered in Elkhart, Indiana, remains a pioneer in high-speed oven technology, with its eikon and conneX series reflecting a consistent focus on streamlined kitchen operations and connectivity-driven workflow management. Panasonic Corporation, from its Osaka base, extends its commercial reach through convection-microwave-broil hybrids such as the NE-SCV3 series, targeting restaurants and cafes that require multi-functionality within a single appliance footprint. UNOX S.p.A. contributes a distinct European engineering perspective from Italy, offering commercial speed ovens such as the SPEED.Pro line that merge convection, steam, and microwave capabilities for versatile culinary outputs. Sharp Corporation has also entered the acceleration curve with its Celerity high speed oven, showcasing advanced thermal engineering capable of reducing whole-chicken cook times to roughly one-third of conventional methods. Additionally, Buffalo Equipment has expanded its proprietary portfolio by unveiling two new high-speed models, reinforcing the trend of domestic and regional manufacturers investing heavily in rapid-cook technology differentiation.
2026–2027 Product Cycle: Real-Time Market Signals
The competitive landscape is being actively reshaped by a concentrated wave of product launches, catalog updates, and application-focused messaging during mid-2026. Ovention Ovens recently refreshed its product catalog with detailed guidance on integrating high-speed ovens into modular kitchen designs and optimizing team workflow allocation. TurboChef simultaneously promoted its Bullet Oven for campus dining environments and high-volume service settings, emphasizing throughput efficiency and space-conscious deployment. Merrychef announced an expansion of its conneX high-speed oven range, positioning the new line as a solution for consolidated kitchen operations and reduced equipment sprawl. Buffalo Equipment followed with the unveiling of two new models within its branded cooking range, signaling continued investment in rapid-cook capacity across retail and foodservice channels. These concurrent developments reflect a broader industry pivot toward operational modularity, deployment flexibility, and menu-agnostic performance.
Inside the Report: Operational Intelligence and Decision Frameworks
Our full market research publication extends well beyond macro-valuation summaries to deliver a tactical decision-support architecture. The report systematically deconstructs market sizing across historical baselines and forward-looking forecast periods, enabling precise revenue modeling and capacity planning. It examines structural segmentation splits that illuminate how built-in versus countertop configurations are performing across distinct commercial environments, while also mapping end-use distribution between restaurant-grade deployments and alternative foodservice applications. Geographic coverage is analyzed through a lens of market maturity, infrastructure readiness, and regional adoption velocity, providing a nuanced view of where demand is stabilizing and where it is accelerating.
The competitive intelligence section profiles active market participants, mapping headquarters locations, technological specializations, and recent developmental activity. Recent product launches, catalog revisions, and targeted promotional campaigns are cataloged to reveal how vendors are responding to shifting operator requirements. Beyond hardware and vendor mapping, the report incorporates regulatory and certification pathways, ensuring that compliance planning is integrated directly into procurement and deployment strategies. Labor cost mitigation scenarios are quantified against conventional cooking benchmarks, and energy efficiency considerations are evaluated alongside certification requirements to provide a complete total-cost-of-ownership perspective. This multidimensional framework is designed to support capital planning, channel strategy formulation, competitive positioning, and menu engineering initiatives with minimal reliance on secondary interpretation.
Strategic Imperatives for Stakeholders
For equipment manufacturers and technology developers, the 9.5 percent growth trajectory and concentrated market share structure underscore the necessity of differentiated engineering, robust ventless and hybrid-cooking portfolios, and proactive compliance alignment. For foodservice operators and franchise groups, the immediate priority lies in evaluating kitchen reconfiguration opportunities that leverage 80 percent faster cook times to compress labor dependency, improve ticket throughput, and expand menu flexibility within constrained footprints. For investors and financial analysts, the diversification across end-use environments and regional growth corridors provides a clear framework for assessing exposure, identifying channel expansion opportunities, and monitoring vendor consolidation patterns. The data demonstrates that high speed ovens are transitioning from tactical kitchen tools to strategic infrastructure assets; companies that embed this reality into their planning cycles will be better positioned to navigate the operational and financial demands of the coming half-decade.
Conclusion: Accessing the Complete Strategic Blueprint
The high speed oven market is entering a phase of sustained, structurally driven expansion marked by technological consolidation, regulatory rigor, and intensifying competitive maneuvering. The aggregate market trajectory, segment dispersion patterns, vendor activity cycles, and compliance frameworks documented in our full research publication provide a comprehensive foundation for informed capital allocation, product planning, and operational optimization. While the overview presented here captures the essential strategic contours, the complete report contains granular sizing breakdowns, detailed vendor profiling, segment-level deployment dynamics, regional adoption mappings, and actionable scenario models that are essential for precise decision-making. To access the full intelligence suite and integrate these findings directly into your 2026 planning cycle, please visit the official market research portal and download the complete publication.
For detailed analysis of this topic, please visit the official page: High Speed Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Paper Pallet Market: Strategic Intelligence for 2026 Decision-Makers
As global supply chains recalibrate around sustainability mandates and regulatory pressures, the packaging sector stands at a pivotal inflection point. The paper pallet market, once a niche alternative to traditional wooden and plastic logistics solutions, has matured into a strategic imperative for enterprises managing high-volume freight across international borders. PW Consulting's latest comprehensive study on the Paper Pallet Market delivers actionable intelligence designed to inform capital allocation, supplier partnerships, and regional expansion strategies throughout the 2026–2032 horizon.
This introduction outlines the strategic architecture of our research, demonstrates how macroeconomic indicators translate into operational foresight, and illustrates why forward-looking organizations are treating paper-based palletization as a core component of their supply chain resilience playbook.
The Macro Trajectory: Growth Signals and Structural Shifts
Between 2020 and 2025, the global paper pallet market demonstrated consistent revenue expansion, reflecting a steady migration away from conventional wood-based packaging. Initial valuation benchmarks in the early 2020s established a foundation that subsequent years reinforced through accelerated adoption across logistics-intensive sectors. The market's progression through 2024 and 2025 reflects an ecosystem that has moved beyond early-adopter experimentation into mainstream procurement considerations.
Our forecast model projects continued revenue growth across the 2026–2032 period, with compound annual growth rates indicating a durable expansion path. This trajectory is not merely a reflection of volume displacement; it captures fundamental shifts in how multinational corporations evaluate total cost of ownership, customs compliance, and environmental reporting. Decision-makers who understand the drivers behind this upward curve position themselves to capture margin advantages before commoditization erodes early-mover benefits.
The scale of the opportunity underscores why organizations cannot rely on fragmented industry anecdotes. A structured, data-anchored view of revenue pathways, demand elasticity, and competitive intensity allows procurement leaders and supply chain executives to evaluate whether paper pallet integration belongs in their near-term roadmap or longer-term sustainability pipeline.
Regulatory Tailwinds and the ISPM-15 Advantage
One of the most consequential dynamics shaping the market involves international phytosanitary regulations. Wooden packaging materials entering cross-border trade corridors must comply with ISPM-15 treatment requirements, which mandate heat treatment or fumigation protocols to mitigate pest transmission risks. Paper pallets, by contrast, fall outside these treatment mandates, eliminating a layer of compliance complexity that has historically slowed freight movement and increased administrative overhead.
This regulatory distinction creates measurable operational advantages for shippers managing high-frequency transatlantic, transpacific, and intra-Asia logistics flows. Paper alternatives reduce dwell time at inspection points, lower the risk of shipment rejection, and simplify documentation workflows. As customs enforcement protocols become more stringent in 2026 and beyond, organizations that standardize paper pallet utilization across export lanes can expect smoother clearance cycles and reduced contingency costs.
Wood Pallet Market
The regulatory environment also intersects with corporate sustainability commitments. Enterprises tracking Scope 3 emissions and packaging circularity targets find that paper-based solutions offer clearer end-of-life pathways when paired with recycling infrastructure, reinforcing the business case beyond mere compliance convenience.
Competitive Architecture: Who Shapes the Market and How
Market leadership in the paper pallet sector is defined not by raw production capacity alone but by proprietary engineering, material science capabilities, and the ability to integrate pallet solutions into broader transit and storage ecosystems. Several organizations have emerged as influential players, each pursuing distinct value propositions that appeal to specific supply chain profiles.
Smurfit Kappa Group, headquartered in Dublin, has built a recognizable presence through engineered paper pallet offerings such as PaPillOn strong paper pallet and TOPPSafe™ pallet top systems. Their approach emphasizes load-bearing performance combined with compatibility into existing corrugated supply networks. DS Smith Plc, based in London, advances a complementary yet differentiated position with its patented fibre-based pallet technology, targeting organizations that prioritize structural consistency and manufacturability at scale.
International Paper Company brings extensive raw material and converting infrastructure to the market, offering corrugated and molded paper pallet formats that leverage decades of industrial packaging expertise. Sonoco Products Company, operating from Hartsville, South Carolina, focuses on integrated paper pallet systems designed for specialized transit requirements and operational durability. PALLITE Limited, headquartered in the United Kingdom, has carved a distinct niche through honeycomb paper pallet designs and PIX® storage solutions that appeal to organizations seeking lightweight yet structurally reliable storage and transport alternatives.
Signode, based in Illinois, has positioned itself around paper pallet options designed for transit environments with ISPM-15 compliance considerations, aligning its portfolio with cross-border shippers seeking regulatory simplicity. ATTA Pallet, located in Hungary, emphasizes production and assembly capabilities tailored to paper pallet manufacturing workflows, while EcoDuro Inc., operating in Canada, contributes molded pulp and paper-based pallet options that broaden the material palette available to sustainability-focused procurement teams.
The competitive field reflects a mosaic of engineering priorities, regional strengths, and integration strategies. Understanding which players are expanding capacity, which are locking in proprietary formulations, and which are building partnerships with logistics integrators is essential for organizations evaluating supplier resilience and pricing stability over multi-year contracting cycles.
Recent Developments Reshaping Product Expectations
The pace of product-level innovation has accelerated markedly in recent months, signaling that incumbents are actively responding to shifting procurement criteria. In September 2025, Smurfit Westrock introduced a recyclable paper pallet wrap engineered as a direct replacement for single-use plastic pallet wraps in shipment applications. This launch reflects a growing emphasis on eliminating plastic wrapping without compromising load containment, a concern that has become increasingly prominent among shippers tracking packaging waste reduction targets.
Earlier, in March 2024, Seaman Paper expanded the functional scope of paper-based transit solutions with the launch of SeaStretch™, a patented lightweight paper alternative designed for shipping and storage loads. This development reinforced the viability of paper as a performance-competitive material in contexts where plastic film had previously dominated, particularly when weight reduction and recyclability are weighted heavily in procurement evaluation frameworks.
These launches matter because they illustrate a market trend moving beyond pallet boards alone. The broader product ecosystem now includes wrapping solutions, load stabilization approaches, and storage geometries that collectively influence total logistics cost. Buyers evaluating paper pallet adoption must consider how compatible wrapping, cushioning, and handling practices affect throughput, damage rates, and downstream recycling feasibility.
What the Report Delivers: Operational Intelligence Beyond Headline Figures
PW Consulting's Paper Pallet Market research is structured to support decision-making at multiple organizational levels. Rather than presenting a static snapshot, the study maps revenue evolution, segment dynamics, and competitive interventions across historical and forecast periods, enabling readers to test assumptions against evidence-based scenarios.
The report examines the structural composition of market demand, identifying how different product types and application categories contribute to overall revenue behavior. It explores regional demand patterns without reducing complexity to oversimplified ratios, offering instead a nuanced view of where adoption momentum is strongest and what local regulatory or logistics conditions amplify or constrain growth.
Detailed company profiles analyze strategic positioning, product differentiation, and recent developmental activity across key participants. This competitive mapping is paired with an assessment of concentration dynamics, helping stakeholders gauge pricing influence, supplier dependency risk, and the likelihood of consolidation pressure in the years ahead.
Operational considerations are addressed through analysis of material developments, product launches, and regulatory alignments that affect procurement planning. Readers gain insight into how transit compliance frameworks, sustainability reporting expectations, and packaging innovation cycles intersect with supplier selection and contract structuring. The research also contextualizes supply chain decision points such as total cost comparisons, damage-risk trade-offs, customs efficiency, and recyclability infrastructure readiness.
Because the study spans a defined historical baseline and extends across a multi-year forecast window, it supports scenario-based evaluation. Organizations can assess how shifts in freight volume, regulatory enforcement intensity, or material cost dynamics may alter adoption timing and budget allocation. This forward-looking structure is particularly valuable for teams planning capital-intensive logistics improvements or evaluating multi-year supplier partnerships.
Why 2026 Is a Defining Year for Strategic Action
The convergence of regulatory clarity, product innovation, and expanding adoption creates a window in which strategic choices carry disproportionate long-term effects. Organizations that delay evaluation risk entering supplier negotiations after pricing structures adjust to heightened demand visibility, while those that assess options prematurely may overlook rapid product improvements that reshape performance comparisons.
In 2026, procurement and supply chain leaders must determine whether paper pallet integration belongs within tactical cost-reduction programs or within broader transformation initiatives tied to compliance, sustainability reporting, and international freight efficiency. Answering that question requires a granular understanding of market direction, competitive behavior, and application-specific demand behavior, all of which our research is designed to clarify.
Firms operating across multiple regions face additional complexity. Regional demand intensity varies, and local regulatory expectations, recycling infrastructure availability, and logistics partner capabilities influence whether paper pallet adoption generates the anticipated benefits. A market-level view must therefore be paired with operational realism about implementation readiness, supplier reliability, and internal change management requirements.
The report enables this level of discernment by connecting macro growth signals with actionable procurement implications. Readers can evaluate whether current supplier options align with their technical specifications, whether product innovation timelines match their implementation horizons, and whether market concentration trends suggest a need for diversification or long-term contracting.
From Insight to Execution
Deep market intelligence becomes valuable only when it informs concrete decisions. PW Consulting's Paper Pallet Market study is built to support that translation. It equips strategy teams with evidence-based context, helps procurement groups benchmark supplier claims against market-wide patterns, and gives executive stakeholders the framing needed to prioritize packaging logistics investments alongside other transformation initiatives.
For organizations preparing for the 2026 decision cycle, the critical task is not simply recognizing that the market is expanding. The strategic value lies in understanding which forces are structural rather than cyclical, which supplier capabilities are likely to endure, and where adoption timing will most strongly affect cost and operational outcomes. Our research is designed to illuminate those distinctions without leaving decision-makers to infer them from partial data.
Paper Pallet Market
The complete analysis provides the depth, segmentation clarity, competitive mapping, and scenario-aware forecasting required to move from awareness to action. For teams tasked with evaluating paper pallet integration as part of broader supply chain strategy, the full report offers the intelligence foundation necessary to make informed, timely, and defensible decisions.
For detailed analysis of this topic, please visit the official page: Paper Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Workplace safety does not develop simply because an organization sends out reminders or reacts when something goes wrong. Sustainable improvement requires a consistent approach that helps people recognize hazards early and address them before they turn into incidents. When everyone uses a shared method for identifying hazards and preventive actions are supported by tools such as inspections, permits, and checklists, safety becomes integrated into everyday operations. It is no longer treated as a separate initiative. Instead, it becomes part of how work is prepared, managed, monitored, and carried out every day.
Understanding Workplace Hazards
A workplace hazard refers to any condition, task, substance, activity, or circumstance that has the potential to cause harm within a working environment. Its effects may include worker injuries, equipment damage, property loss, or disruptions to routine business activities. Hazards can arise from machinery, production processes, materials, workplace conditions, or the way specific jobs are performed.
Problems can occur when employees, supervisors, and contractors have different ideas about what constitutes a hazard. Reports may become inconsistent, risk assessments may reach different conclusions, and controls may be selected without addressing the actual danger. A useful way to create consistency is to group hazards into six broad categories. This gives teams a common framework for recognizing risks, classifying them correctly, and selecting appropriate preventive measures.
Six Major Categories of Workplace Hazards
- Safety Hazards
Safety hazards are usually among the easiest risks to notice because they can result in immediate injury. Examples include unprotected edges, floor openings, obstructed walkways, moving machinery or vehicles, and defective equipment. Since these hazards can produce consequences quickly, controls should be established before work begins.
Measures such as physical guarding, equipment isolation, permit requirements, and scheduled workplace inspections can help verify that necessary protections are present. They also help ensure safe conditions remain in place for the duration of the activity rather than being checked only at the beginning.
- Chemical Hazards
Chemical hazards are not always obvious. A substance may appear harmless while still having the potential to cause burns, poisoning, respiratory difficulties, or longer term health effects. Hazardous chemicals can be present in many forms, including liquids, gases, fumes, dust, vapors, and residual contamination.
Where possible, organizations can begin by replacing a hazardous substance with a safer alternative. Additional controls may involve containment, ventilation, clear labeling, exposure limitations, and suitable personal protective equipment. For higher risk activities, inspections and permit processes provide additional assurance that essential safeguards have been established before and while the work is taking place.
- Biological Hazards
Biological hazards arise when workers may come into contact with organisms or contaminated materials capable of causing infection or disease. These may include bacteria, viruses, fungi, insects, and other biological agents. Such risks can occur in healthcare facilities, laboratories, waste handling operations, food production areas, and outdoor work environments.
Effective management depends on reliable hygiene procedures, proper sanitation and cleaning, controlled access where necessary, and appropriate health related programs. Because these controls need to remain effective consistently, documented processes can help teams follow the required precautions instead of depending entirely on individual judgment.
- Physical Hazards
Some hazards may not produce an immediate visible effect, making them easier to overlook. Continued exposure to noise, vibration, radiation, poor lighting, or extreme temperatures can gradually affect worker health as well as job performance.
Organizations can monitor exposure, introduce engineering controls such as barriers or shielding, maintain equipment correctly, and adjust work schedules where necessary to reduce extended exposure. Addressing these conditions early can help prevent employees from experiencing prolonged contact with potentially harmful workplace environments.
- Ergonomic Hazards
Not every workplace injury happens suddenly. Repetitive tasks, awkward movements, poor posture, heavy lifting, and poorly arranged workstations can create physical problems over time. These ergonomic hazards can contribute to musculoskeletal injuries while also affecting productivity and operational efficiency.
Organizations can lower these risks by improving workstation layouts, redesigning tools, changing work methods, introducing safer lifting techniques, rotating tasks, and allowing appropriate recovery periods. When these practices are incorporated into standard procedures and reviewed through routine workplace assessments, they are more likely to remain effective rather than becoming temporary improvements.
- Psychosocial Hazards
Workplace safety also involves conditions that can affect employees beyond their physical surroundings. Excessive workloads, long working hours, unclear expectations, harassment, isolation, and inadequate support can influence concentration, judgment, and overall mental well being. These pressures may increase the possibility of mistakes and workplace incidents.
Managing psychosocial risks requires purposeful planning at the organizational level. Reasonable staffing, realistic schedules, clearly defined responsibilities, and dependable channels for raising concerns can contribute to a healthier working environment. A supportive workplace culture can strengthen these efforts by encouraging communication, appropriate assistance, and responsible reporting of problems.
Turning Risk Management into a Daily Habit
Identifying a hazard is only one part of effective safety management. The real objective is to ensure that corrective actions are implemented and continue working as intended. A practical safety cycle includes identifying the hazard, assessing the associated risk, determining suitable controls, and confirming that those controls are consistently followed whenever the activity occurs.
Digital workflows can help organizations apply this process more consistently across different teams, departments, and locations. Electronic permit to work systems can provide greater control over higher risk activities, including confined space entry and hot work. Lockout tagout procedures can be connected with equipment assets, helping teams verify that required isolation steps have been completed. Mobile checklists can also request supporting evidence, including photographs or QR code confirmation, before work receives authorization.
Used together, these capabilities can reduce procedural gaps, support compliance, and improve operational efficiency without removing essential safety requirements.
Connecting Safety Policies with Everyday Work
Paper based processes can result in incomplete records, delayed approvals, and inconsistent use of established procedures. Digital systems provide a more structured approach to managing accountability and compliance. When hazard categories, risk assessment methods, and control libraries are brought together within a common system, safety requirements can become easier for teams to understand and apply.
Supervisors can access required controls more quickly, employees can work from clearer instructions, and managers can use current information to monitor performance. Standardized templates can also promote consistency across different sites while giving teams enough flexibility to consider local conditions, contractor activities, and changing operational requirements.
A practical starting point is to examine routine work through the six hazard categories. Controls that are frequently required can then be incorporated into inspection and permit workflows as required steps. Mobile risk assessments can be completed directly where work is being performed, while dashboards can improve visibility by highlighting overdue actions and recurring issues that require additional attention.
When organizations apply this structured approach consistently, they can improve the management of near misses, reduce delays in approval processes, and strengthen audit performance. More importantly, safety stops being viewed simply as a compliance obligation. It becomes a dependable part of how the organization plans work, manages risk, and achieves operational excellence.
Book a free demo @ https://toolkitx.com/blogsdetails.aspx?title=Types-of-workplace-hazards:-examples,-and-how-to-control-them
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Safety-culture:-what-it-is,-why-it-matters,-and-how-to-build-it
https://toolkitx.com/blogsdetails.aspx?title=Hot-work-permit:-definition,-requirements,-and-practical-guide-to-going-digital
PW Consulting: Meal Kit Market Hits $39.44B in 2025, Forecast 8.4% CAGR to $69.37B by 2032
By PW Consulting, 2026-09-16
Strategic Compass for the Meal Kit Delivery Services Market: Navigating the 2026–2032 Growth Cycle
The global meal kit delivery services market is entering a decisive phase. As consumer habits around convenience, nutrition, and sustainability continue to reshape home cooking, market participants face a complex matrix of expansion opportunities, cost pressures, and compliance risks. This analysis frames the commercial landscape that will define enterprise strategy through the end of the decade, drawing on a comprehensive market research study designed to support high-stakes decision-making in 2026 and beyond.
Why 2026 Demands a Refined Market View
Meal kit delivery services are no longer an experimental convenience category. They have matured into a structural alternative to traditional grocery and dining-out behaviors. The sector is expanding against a backdrop of shifting household budgets, evolving dietary preferences, and increasing scrutiny of food safety and supply chain resilience. For executives, the central challenge is no longer whether demand exists, but how to position operations, pricing, and portfolio strategy amid volatility.
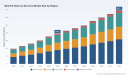
The most recent market data underscores the scale and momentum of this environment. The global meal kit delivery services market generated approximately USD 39.44 billion in revenue in 2025, up from roughly USD 19.61 billion in 2020. Over that same historical window, the market advanced through a sustained growth trajectory that carried valuations from USD 23.12 billion in 2021 to USD 35.4 billion in 2024, reflecting the category’s deepening penetration across consumer segments. Looking forward, the forecast period from 2026 to 2032 points to continued expansion, with the market projected to reach USD 42.87 billion in 2026 and advance toward USD 69.37 billion by 2032. The implied compound annual growth rate across the forecast horizon is 8.4 percent.
These headline figures matter because they frame the stakes. Growth at this pace is strong enough to justify bold investment, yet not so automatic that it absorbs operational missteps. A company that treats meal kits as a purely transactional offering risks losing share to competitors who integrate brand trust, recipe innovation, and supply chain discipline into a cohesive value proposition. Conversely, operators that align their roadmap to the structural drivers behind this expansion can convert category growth into durable competitive advantage.
Worldwide Pet Food Delivery Market
Macro Signals Shaping the Competitive Terrain
The market’s trajectory is being influenced by more than consumer sentiment alone. Inflationary pressure on raw materials, regulatory scrutiny around food safety, and heightened expectations for quality and transparency are reshaping the operating environment. These forces are not peripheral concerns; they directly affect margin structures, product design, and the credibility of brands that depend on recurring subscription behavior.
On the supply side, farm-level vegetable prices are predicted to increase 20.5 percent in 2026, with a prediction interval ranging from 3.6 percent to 42.7 percent. This degree of uncertainty complicates ingredient planning for providers that rely on fresh produce as a core component of their value proposition. Compounding this, retail fresh vegetable prices increased by 3.1 percent from March 2026 to April 2026 and were 11.5 percent higher in April 2026 than in April 2025. For meal kit companies, the implication is clear: input cost variability can quickly translate into pricing tension, recipe reformulation, or margin erosion if sourcing and hedging strategies are not built for volatility.
At the same time, food safety remains a defining trust factor. A multistate Salmonella outbreak linked to home delivery meals from Metabolic Meals resulted in 16 illnesses and 7 hospitalizations, with the CDC investigation closing after the outbreak was resolved. In a separate event, cheese ingredients included in certain HelloFresh brand meal kits were recalled in Canada due to Listeria monocytogenes contamination. These incidents illustrate how quickly a compliance or quality failure can disrupt brand perception and operational continuity. In a category built on recurring delivery and household trust, such events are not merely reputational setbacks; they are strategic risk signals that should inform vendor oversight, traceability investments, and recall readiness.
What the Research Report Delivers
This market research study is structured to move beyond broad narrative and into actionable intelligence. It is designed for strategy, product, sales, and investor teams that need a shared fact base for planning, prioritization, and external communication. The report brings together market sizing, segmentation logic, competitive profiling, and industry context in a format that supports both internal alignment and external stakeholder engagement.
The analysis covers historical performance from 2020 through 2025 and extends forecast perspective across 2026 to 2032. This dual lens helps organizations distinguish between cyclical fluctuations and structural trends, enabling more disciplined scenario planning. Rather than treating growth as a single line item, the report unpacks the categories, offerings, and meal types that constitute the market’s underlying architecture, allowing decision-makers to identify where demand is concentrated and where variance is likely to emerge.
Throughout the study, attention is given to the practical implications of the data. Market size is presented with the context needed to interpret momentum, while segmentation insights are framed to support portfolio decisions, market-entry logic, and resource allocation. The report also examines market concentration to illuminate the balance between established players and the room available for differentiation. The objective is to provide a stable analytical foundation on which operational strategy can be built.
How the Market Is Structured
The meal kit delivery services market is shaped by multiple overlapping demand drivers. Some consumers prioritize the experience of cooking from scratch with guided recipes and pre-portioned ingredients, while others seek speed and simplicity with minimal preparation. Dietary identity also plays a significant role, with a meaningful portion of demand oriented toward plant-based and vegetarian options, and a larger share anchored in non-vegetarian meals. These preferences influence not only product design, but also customer acquisition messaging, retention dynamics, and the cost profiles of different service models.
Offering formats split the market between services that emphasize cooking from ingredients and those oriented toward quicker, more immediate consumption. The balance between these approaches affects logistics, packaging, customer expectations, and margin potential. Meal type segmentation further differentiates demand, creating distinct strategic paths for brands that compete on variety, culinary authenticity, convenience, or health and sustainability credentials. Regionally, the market reflects varying levels of adoption, with differing consumer expectations around price sensitivity, distribution reach, and brand trust.
In concentrated markets, the behavior of leading providers often sets pace and expectations for the broader field. Concentration patterns can inform how aggressively new entrants can pursue differentiation, how incumbents defend share, and where partnerships or niche positioning may create viable openings. The report contextualizes these structural relationships without reducing them to oversimplified rankings, because competitive advantage in meal kits often depends on execution details that numbers alone cannot capture.
Competitive Landscape: Ten Profiles, Multiple Strategic Playbooks
The competitive field includes a diverse set of operators, each pursuing a distinct interpretation of what consumers should receive from a meal kit service. The companies profiled in the research represent a cross-section of business models, recipe philosophies, and distribution approaches that together define the current market rhythm.
- HelloFresh SE, headquartered in Berlin, Germany, provides meal kit delivery services with more than 100 weekly recipes, alongside add-ons, seasonal boxes, premium meals, and vending machine distribution. Its breadth of format and recipe volume points to a scale-oriented strategy that seeks to serve a wide range of household needs under one brand umbrella.
- Marley Spoon, based in Sydney, Australia, offers meal kit delivery services featuring gourmet recipes, budget plans, and collaborations such as with Martha Stewart. Its profile suggests a dual focus on elevated culinary appeal and accessible price points, using partnerships to extend brand reach and recipe credibility.
- Purple Carrot, headquartered in Santa Barbara, California, specializes in meal kit delivery services focused on plant-based and vegetarian options. Its narrower dietary emphasis positions it within a segment where mission alignment and ingredient storytelling can support loyalty and differentiation.
- Hungryroot, based in Chicago, Illinois, provides fresh meal kit delivery services with customizable recipes and ingredient sourcing. Customization and sourcing transparency indicate a model built around flexibility and consumer control, which can be especially relevant for households balancing dietary preferences with convenience.
- Sunbasket, located in Burlingame, California, delivers organic meal kit services with nutrient-dense recipes and sustainable ingredients. Its emphasis on organic and sustainability attributes aligns with consumers who treat food quality and sourcing as central purchase drivers.
- Gobble, headquartered in Columbus, Ohio, offers meal kit delivery services emphasizing quick and easy home cooking recipes. Its value proposition leans toward time savings and usability, appealing to consumers who want cooking engagement without extended prep burden.
- Freshly Inc., based in New York, New York, provides meal kit delivery services with fresh, pre-portioned ingredients for at-home meals. Its approach reinforces convenience and freshness as core purchase triggers, positioning the service as a practical bridge between groceries and ready-made dining.
- Dinnerly, headquartered in Denver, Colorado, delivers budget-friendly meal kit services with simplified recipes for everyday use. The focus on affordability and simplicity targets cost-conscious households and those seeking repeatable, low-friction meal routines.
- Green Chef, also based in Denver, Colorado, specializes in organic and plant-based meal kit delivery services. By combining organic positioning with plant-centric offerings, it operates at the intersection of health, dietary preference, and ingredient quality.
- Home Chef, located in Chicago, Illinois, offers meal kit delivery services with chef-created recipes and value options. Its combination of culinary identity and value-tiered choices reflects an effort to serve both experience-seeking and price-sensitive consumers.
- Tovala, headquartered in San Francisco, California, provides scan-to-cook meal kit delivery services with smart oven integration for precise heating. This model blends meal kits with connected appliance functionality, illustrating how hardware, software, and food service can converge around convenience and repeatability.
These profiles matter because they show that the market is not converging on a single formula. Some providers compete through scale, recipe variety, and multi-format distribution. Others compete through dietary specialization, sustainability claims, customization, or appliance-linked convenience. For a company planning its next move, the strategic question is less about which model is universally best and more about which combination of audience, operational capability, and brand promise can be sustained at scale.
From Consumer Preference to Operating Risk
Market growth does not happen in a vacuum. The same forces that expand demand can also expose weak points in execution. Ingredient inflation, for example, is not only a cost issue; it is a design issue. If farm-level input prices can swing materially within a single year, then menus, portion sizing, sourcing partnerships, and pricing architecture must be flexible enough to absorb change without eroding consumer trust. Brands that lock themselves into rigid recipes or uncompetitive price points may find themselves squeezed from both sides.
Food safety adds another layer of strategic urgency. The recall events involving HelloFresh and the Salmonella outbreak associated with Metabolic Meals demonstrate that meal kit providers operate in an environment where quality failures can become public quickly and carry both health and business consequences. In this context, operational discipline is a competitive asset. Traceability, supplier vetting, testing protocols, and recall procedures should be treated as part of the core value proposition, not as back-office compliance functions. Companies that institutionalize these practices are better positioned to protect retention and reduce the likelihood that a single incident derails growth momentum.
These dynamics also intersect with customer acquisition and retention economics. Meal kit services depend heavily on recurring engagement, which means the cost of disappointing a customer is multiplied over time. Quality, reliability, and transparent communication can therefore be viewed as retention investments with direct financial returns. In a market projected to grow from USD 42.87 billion in 2026 toward nearly USD 70 billion by 2032, the winners are likely to be those who combine expansion with consistency.
Using the Study to Inform 2026 Decisions
For organizations active in or entering this market, the study functions as a strategic decision-support tool. It helps leadership teams answer questions that are otherwise difficult to resolve with fragmented public information: where demand is accumulating, which segments carry the strongest growth logic, how competitive intensity varies across formats, and what external pressures may shape margin and operational planning in the near term.
The report’s historical and forecast structure supports a range of applications. Strategy teams can use it to evaluate expansion timing and geographic or segment prioritization. Product and operations teams can use it to frame menu architecture, sourcing resilience, and service-model trade-offs. Marketing and brand teams can use the segmentation context to sharpen positioning without relying on broad assumptions. Investors and advisors can use the concentration and growth outlook to assess market maturity and the durability of competitive claims.
Importantly, the study is designed to be actionable without being over-specified at the summary level. It provides the analytical scaffolding needed to make informed choices while leaving room for company-specific interpretation. The most valuable insights often emerge when broad market direction is combined with internal capabilities, customer data, and operational constraints. That is where the research is intended to be most useful: as a reliable base layer for strategic judgment.
What Remains in the Full Analysis
The overview above outlines the strategic context and structural themes that shape the meal kit delivery services market. It also demonstrates why 2026 is a pivotal year for planning: input-cost uncertainty, food safety scrutiny, and continued category expansion are all active at once. Yet the full report contains a deeper level of segmentation value, competitive benchmarking, and scenario-ready detail that cannot be fully reproduced in an executive summary.
Meal Kit Delivery Services Market
For teams that need to move from general market awareness to specific planning assumptions, the complete study provides the granularity required to support concrete decisions. The full analysis examines how the market breaks down across regions, offerings, and meal types, and it contextualizes those splits within the broader growth trajectory. It also expands the competitive and operational picture in ways that help organizations identify where to concentrate resources, where to defend position, and where to experiment responsibly.
If your objective is to align 2026 strategy with a market projected to grow at 8.4 percent through 2032, the complete research offers the evidence base needed to make that alignment precise rather than approximate. The full report is available on the PW Consulting market research page, where the detailed segmentation, competitive profiles, and supporting market context can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Meal Kit Delivery Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Organizations involved in high risk work are increasingly reassessing permit processes that still rely on printed forms, handwritten signoffs, and documents physically moving between people and locations. Even with major advances in workplace technology, paper based permits continue to play a role in many operations where hazardous tasks require careful authorization and control.
Being familiar with a process does not necessarily make it effective. Paperwork can delay approvals, increase the possibility of incomplete or inaccurate details, and make compliance evidence difficult to assemble during audits, reviews, or incident investigations. A sustainable paperless Permit to Work (PTW) model replaces these manual exchanges with a connected digital workflow. The result can be better visibility, clearer accountability, quicker coordination, and reduced administrative waste.
What Is a Paperless Permit to Work System?
A paperless PTW system is a digital platform designed to plan, authorize, monitor, and close high risk work such as hot work, confined space entry, excavation, electrical maintenance, work at height, and other hazardous activities. Instead of carrying forms between departments, offices, control areas, or job sites, personnel manage permit tasks within a centralized shared digital environment.
Details created during the entire permit lifecycle can be captured electronically. Risk assessments, supporting files, approvals, and closure information stay connected, providing a complete and traceable record of the activity. Electronic authorization removes the dependence on handwritten signatures, while automated workflow tracking shows how a permit progresses. Timestamps can also establish when specific actions, reviews, and approvals took place.
Using one consistent digital process can improve standardization and information quality as well. When an audit, review, or investigation requires historical evidence, teams can retrieve the relevant permit information from one accessible location rather than sorting through physical folders.
Sustainability Goes Beyond Eliminating Paper
Eliminating printed forms is an immediate advantage of digital PTW, but the sustainability benefits do not stop with reduced paper use.
Digital availability removes several inefficiencies associated with physical permit administration. Supervisors and workers can access the information they need without repeatedly traveling between offices, control points, and work areas to obtain signatures, approvals, or updates. Reducing these physical exchanges can save time and limit unnecessary use of resources.
Digital workflows can also reduce rework caused by documentation issues. A paper permit can be delayed when information is missing, handwriting is difficult to interpret, pages become damaged, or someone uses an outdated version. Digital systems can reduce these problems through standardized templates, controlled document versions, and mandatory fields that need to be completed before the workflow advances.
Standardized permit formats create additional efficiency because teams can rely on approved structures instead of recreating paperwork for individual jobs. Connected safety controls may also help reduce the likelihood of incidents that lead to investigations, downtime, repairs, or recovery work.
Core Capabilities of an Effective Digital PTW Platform
An effective paperless PTW solution should provide more than a digital copy of an existing paper form. Important capabilities include:
- Flexible permit templates that define hazards, controls, and approval requirements while accommodating appropriate differences between sites.
- Integrated risk assessment processes that incorporate toolbox talks, job safety analyses, gas testing, isolation steps, and other relevant precautions into the permit workflow.
- Automated approval routes and electronic signatures that send permits to the correct reviewers while preserving a complete record of authorization.
- Mobile functionality that enables field personnel to create, review, approve, inspect, and close permits while capturing photographs, readings, measurements, and observations during the job.
- Controlled contractor access that allows external personnel to participate in the required activities without reducing security or governance.
- Live dashboards and alerts that highlight upcoming permit expirations, unfinished actions, and potential conflicts between concurrent activities.
- Detailed audit trails that retain permit revisions, approvals, historical activity, and important decisions.
- Integration with work management, asset management, and incident reporting tools to provide a broader picture of operational risk.
Strengthening Safety With Digital Oversight
Traditional paper permit processes often depend on individuals transferring information and manually interpreting requirements. This reliance can create delays, inconsistencies, or misunderstandings that affect both safe work execution and operational productivity.
Digital PTW platforms introduce greater structure by applying a defined method for preparing and managing permits. Mandatory fields can stop essential information from being overlooked before submission. Automated rules can further reinforce safety requirements, such as requiring gas test details before approval of a hot work permit.
Certain digital systems can also recognize activities scheduled in the same area and generate warnings when simultaneous work could create a potential safety conflict.
Improved visibility benefits everyone involved in the permit process. Supervisors can identify delayed approvals and incomplete actions more easily. Field personnel can receive clearer requirements and more consistent instructions. HSE teams can examine operational information to identify recurring issues, review safety performance, and consider whether existing controls are producing the intended results.
Business and Environmental Advantages
Digital permit management can create benefits that extend beyond workplace safety.
Removing delays associated with physical signatures can shorten approval cycles and improve coordination between teams. Structured electronic information also creates records that are easier to use for trend analysis, workforce development, and continuous improvement.
Organizations can reduce expenses associated with printing, physical storage, document transportation, and disposal. For companies operating across multiple facilities, centralized digital workflows can make consistent permit practices easier to establish across locations while also simplifying the management of procedural changes and document updates.
Best Practices for Implementation
A transition to paperless PTW works most effectively when it is introduced through a planned, staged approach. Organizations can begin by identifying permit categories associated with their most significant operational and safety risks.
Existing procedures can then be converted into standardized digital workflows, supported by clear controls for document versions and process changes. Training should match the responsibilities of each user group so workers, supervisors, reviewers, and approvers understand how their duties fit into the new process.
Performance should be reviewed using indicators such as approval times, permit conflicts, near miss patterns, and the quality of permit closure. Monitoring these measures can show whether the system is achieving its intended outcomes and identify areas where further improvements may be necessary.
Offline functionality can be particularly useful for teams working at remote sites or in areas where connectivity is unreliable. Users can continue completing permit activities without an active network connection and synchronize the information once connectivity becomes available again.
Conclusion
A paperless Permit to Work system provides a practical and sustainable approach to controlling hazardous work through an organized digital process. Replacing manual paperwork can improve compliance, reduce administrative errors, accelerate authorization, increase visibility, and support stronger safety performance while also contributing to environmental objectives.
For organizations that continue to depend on printed permits and manual follow ups, adopting digital PTW management can represent a meaningful move toward safer operations, stronger governance, smoother coordination, and more sustainable long term performance.
Book a free demo @ https://toolkitx.com/blogsdetails.aspx?title=Sustainable-permit-to-work-(PTW):-go-paperless-and-keep-safety-tight
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Safety-culture:-what-it-is,-why-it-matters,-and-how-to-build-it
https://toolkitx.com/blogsdetails.aspx?title=Hot-work-permit:-definition,-requirements,-and-practical-guide-to-going-digital
PW Consulting: Smart Manufacturing Market Hits $215B in 2025, Projected 13.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Intelligent Factory: Strategic Imperatives for the Smart Manufacturing Market in 2026
The industrial landscape is undergoing a fundamental reset. As enterprises transition from pilot projects to enterprise-wide deployment, smart manufacturing has moved from a competitive advantage to an operational necessity. For executives planning capital allocation, technology roadmaps, and supply chain resilience in 2026, the window for strategic action is narrowing. This introduction outlines the strategic framework embedded in our latest market research, designed to equip decision-makers with the analytical rigor required to navigate an increasingly complex ecosystem.
A Market in Accelerated Expansion
The smart manufacturing sector has demonstrated consistent momentum over the past half-decade, evolving from incremental automation to integrated, data-driven production environments. Our analysis tracks this trajectory from 2020 through the base year of 2025, establishing a clear upward curve that sets the stage for the forecast window extending to 2032. The compound annual growth rate of 13.5 percent across the projection period signals more than incremental uptake; it reflects a structural shift in how manufacturers invest in infrastructure, software, and operational intelligence.
Revenue expansion tells a parallel story. The market crossed the two hundred billion dollar threshold in 2024 and reached approximately two hundred fifteen billion dollars by 2025. Forward momentum carries this trajectory through the mid-to-late 2020s, with valuations climbing steadily toward the three hundred forty billion dollar range by 2032. These figures are not abstract metrics; they represent capital deployment patterns, procurement cycles, and technology prioritization decisions that will define competitive positioning for the remainder of the decade.
Yet macro-level growth is only the starting point. The real strategic challenge lies in understanding how capital flows across technology stacks, how regional supply chains are reconfiguring under policy pressures, and which operational models will prove sustainable as deployment scales. This report is built to answer those questions with precision.
Report Architecture and Operational Utility
A market study earns its value only when it translates into actionable strategy. Our research is structured to serve multiple stakeholder functions simultaneously, from executive briefing to operational planning. The core of the analysis is built around four interconnected pillars:
- Technology segmentation analysis that dissects adoption patterns across control systems, execution platforms, and programmable logic architectures, revealing where investment is concentrating and which capabilities are becoming baseline expectations.
- Component-level evaluation distinguishing hardware procurement cycles from software licensing and services integration, helping procurement and IT leaders align budgeting rhythms with deployment realities.
- End-use industry mapping that highlights how automotive, electronics, aerospace, and defense organizations are tailoring smart manufacturing investments to their specific throughput, compliance, and precision requirements.
- Geographic distribution insights that contextualize regional demand intensity, policy acceleration, and supply chain localization trends without reducing complex dynamics to simplistic rankings.
Beyond segmentation, the report delivers competitor profiling, partnership mapping, and a regulatory watch module that tracks how industrial policy is reshaping procurement and localization mandates. Each section is designed to feed directly into scenario planning, vendor evaluation, and capacity expansion decisions. Readers will find executive dashboards, adoption maturity curves, and investment prioritization matrices that convert raw analysis into boardroom-ready narrative.
Competitive Dynamics Among Market Leaders
The smart manufacturing arena is defined by a concentrated but heterogeneous group of players, each anchoring its strategy around distinct value propositions. Our competitive assessment examines how these organizations position themselves across automation, digital factory platforms, and industrial connectivity.
Smart Factory Market
Siemens AG continues to anchor its offering around integrated digital factory ecosystems, bundling automation, production operations, and Industry 4.0 platforms into a unified deployment model. ABB Ltd has carved a parallel path with a focus on robotics, automation, and AI-driven optimization, positioning intelligent control as a differentiator rather than a feature. Rockwell Automation, Inc. emphasizes industrial automation platforms, MES systems, and digital twin technologies, reflecting a growing enterprise appetite for simulation-led process refinement before physical deployment.
Schneider Electric SE brings an energy-centric lens to the market, developing eco-adaptive infrastructure and smart grid solutions that integrate directly into manufacturing environments. Honeywell International Inc. contributes a connective enterprise perspective, pairing industrial cybersecurity with IIoT platforms to address the operational risk dimension that becomes more acute as factories digitize. Emerson Electric Co. reinforces this momentum with automation solutions, digital twins, and smart equipment designed to streamline industrial operations at scale.
GE has maintained leadership in advanced manufacturing technologies, particularly through industrial IoT and predictive maintenance systems that extend asset life and reduce unplanned downtime. Mitsubishi Electric Corporation complements the field with factory automation, robotics, and IoT-enabled smart factory systems, while Robert Bosch GmbH focuses on industrial automation, IoT, and digital transformation solutions that support smart production across diverse manufacturing modalities.
The competitive field also includes specialized and adjacent players that shape niche but high-impact segments. Applied Materials, Inc. delivers semiconductor equipment and smart manufacturing platforms purpose-built for chip production, an industry where precision and process control carry outsized strategic weight. Cimatron Ltd. supplies CAM software and integrated workflow solutions that bridge design and shop-floor execution. HighByte Inc. addresses the data plumbing challenge directly, providing industrial data management and connectivity software that underpins effective smart factory integration.
Together, these players illustrate a market where differentiation is increasingly tied to integration depth, data interoperability, and sector-specific expertise rather than hardware specifications alone. Understanding these positioning strategies is essential for procurement leaders evaluating vendor roadmaps and for operators assessing which ecosystems are most likely to support long-term scalability.
Policy, Regulation, and Regional Dynamics
Market growth does not occur in a policy vacuum. Industrial strategy, trade dynamics, and regulatory frameworks are actively reshaping where and how smart manufacturing investments are deployed. Recent developments provide a clear signal that governments and standards bodies are accelerating their focus on manufacturing modernization.
China's industrial upgrading program continues to influence global supply chain architecture. By mid-2025, assessments documented substantial progress in localization rates across key sectors, including agricultural machinery and basic materials. At the same time, high-performance computing segments have shown more uneven progress, with import dependency remaining elevated in certain categories. The nine implementation paths associated with the initiative prioritize digitalization of manufacturing equipment, intelligent process design, and green standards aimed at reducing resource consumption. These priorities intersect directly with smart manufacturing adoption, especially in energy-intensive sectors where China already holds dominant production share in lithium-ion batteries and solar modules.
On the other side of the Pacific, policy incentives are reinforcing domestic investment. Analysis released in late 2025 highlighted U.S. government incentives and OEM-led digital transformation efforts as key drivers of smart manufacturing adoption, alongside state-level support mechanisms for pilot programs. This alignment between federal encouragement and corporate deployment is creating a more structured pathway for scaling intelligent manufacturing capabilities.
Standards development is also gaining momentum. India's telecommunications engineering framework introduced a technical report in mid-2025 establishing standards for Industry 4.0 and smart manufacturing integration, reflecting a broader international push to harmonize interoperability expectations and reduce fragmentation in connected factory environments.
Meanwhile, industry events and conference agendas are increasingly centered on autonomy, agentic AI integration, and advanced packaging in semiconductor manufacturing, signaling where practitioner attention and R&D emphasis are converging. These developments do not merely contextualize the market; they shape procurement timelines, compliance strategies, and cross-border investment decisions.
Why This Research Matters for 2026 Decision-Making
Executive teams entering 2026 face a set of interlocking decisions: which technology layers to standardize, how to sequence capital deployment, which vendor ecosystems to align with, and how to hedge against regulatory and supply chain volatility. High-level growth projections can inform optimism, but they cannot replace granular intelligence about adoption bottlenecks, segment-specific demand intensity, and competitive maneuvering.
This report is designed to close that gap. It converts market scale into strategic context, situates competitor moves within broader technology trends, and embeds policy developments into operational planning assumptions. For organizations evaluating factory modernization, capacity expansion, or digital transformation roadmaps, the analysis provides a structured reference point for scenario modeling and risk assessment.
The full study goes further than what an introduction can capture. It contains segment-specific adoption trajectories, regional intensity mapping, detailed competitor positioning tables, procurement cycle insights, and scenario-based forecasts that allow leadership teams to test assumptions against multiple future states. Those elements are essential for converting directional awareness into precise investment logic.
Accessing the Complete Intelligence
The smart manufacturing market is expanding at a pace that rewards disciplined analysis. With a sustained growth trajectory, intensifying competition among established and specialized players, and an evolving policy environment that directly affects localization and standards, the cost of incomplete information is rising. Organizations that enter 2026 with a clear view of technology segmentation, competitive positioning, and regulatory direction will be better positioned to allocate capital efficiently, negotiate from an informed stance, and build manufacturing capabilities that remain resilient as the landscape shifts.
Smart Manufacturing Market
To explore the complete dataset, segmentation breakdowns, and competitor profiles in full detail, download the full report. The complete analysis provides the depth required to move from strategic awareness to execution-ready decision-making.
For detailed analysis of this topic, please visit the official page: Smart Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Structural Steel Pipe Market to Hit $489.1M by 2032, 3.45% CAGR
By PW Consulting, 2026-09-16
Strategic Imperatives in the Structural Steel Pipe Market: Navigating the 2026-2032 Cycle
The structural steel pipe industry stands at a critical juncture as it moves through the 2026 fiscal year. For executives, procurement leaders, and investors, understanding the trajectory of this market is no longer optional—it is a prerequisite for resilient supply chain design and capital allocation. Our latest market research delivers a comprehensive examination of the forces shaping demand, pricing, and competitive positioning across the global structural steel pipe landscape. This introduction outlines the strategic value embedded in the full report, highlights the macro trends that demand attention, and explains how data-driven foresight can convert market volatility into competitive advantage.
The Macro Trajectory: Recovery, Expansion, and Measured Growth
Historical data reveals a market that has steadily climbed out of the pandemic-era disruptions and into a phase of structured expansion. Between 2020 and 2025, total market revenue moved from approximately 298.45 million USD to 386.5 million USD, reflecting a compound annual growth rate that underscores the sector's underlying resilience. The upward momentum carries into the forecast window: 2026 opens at an estimated 399.37 million USD, and the trajectory advances toward 489.1 million USD by 2032, supported by a projected CAGR of 3.45 percent.
While these aggregate figures establish the baseline, the real strategic insight lies in understanding why growth is unfolding at this pace and where the inflection points will emerge. The forecast period through 2032 does not imply a straight line. Year-over-year movement shows nuanced fluctuations that reward stakeholders who look beyond headline numbers. Readers who engage with the full report will find a detailed quarter-by-quarter and year-by-year narrative that connects macroeconomic signals—such as interest rate environments, infrastructure appropriations, and industrial construction cycles—to the demand patterns driving pipe procurement across multiple downstream sectors.
Diversified Demand Centers and the Changing Application Mix
Structural steel pipe is no longer a single-purpose commodity. Its deployment spans oil and gas infrastructure, commercial and civil construction, water and wastewater systems, and an expanding set of industrial applications that rely on high-integrity tubular products. The market's breadth means that shifts in any one vertical can materially alter procurement strategies, inventory planning, and pricing negotiations.
Our research dissects the application landscape without reducing it to simplistic rankings. The full report maps how project pipelines, regulatory mandates, and regional infrastructure spending are redistributing demand across use cases. It also examines the degree to which certain applications are becoming more cyclical while others exhibit steadier, policy-driven consumption. For executives planning multi-year supply agreements or evaluating capacity investments, this granularity matters. It allows organizations to anticipate which segments will tighten during downturns and which will remain robust, enabling more precise hedging of procurement exposure.
Equally important is the interplay between application demand and product type. Seamless pipes, welded pipes, and spiral welded variants each serve distinct performance and cost profiles. The report analyzes how engineering requirements, cost pressures, and manufacturing capabilities are shaping the adoption mix across these categories. Decision-makers who understand these dynamics can better align sourcing strategies with technical specifications, avoiding over-specification in cost-sensitive programs or under-specification in high-stress applications.
Geographies in Motion: Regional Dynamics That Reshape Sourcing
No market analysis is complete without a rigorous view of regional performance. The structural steel pipe market reflects divergent economic conditions, trade policies, and construction cycles across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each geography carries its own set of demand drivers, supply constraints, and policy risks that directly influence landed costs and availability.
In the full report, we avoid surface-level regional snapshots. Instead, we provide an integrated assessment of how cross-border trade flows, local production capacity, and infrastructure investment programs interact to create pricing divergence and availability gaps. This regional lens is especially valuable for multinational operators and distributors who must coordinate procurement across multiple markets. The analysis identifies where local supply is tightening, where import dependency creates exposure, and where domestic production is gaining strategic importance. Readers will see how these regional conditions translate into actionable sourcing recommendations rather than abstract market commentary.
Competitive Landscape: Vertically Integrated Leaders and the Battleground for Share
The competitive structure of the structural steel pipe market is defined by a mix of large, globally integrated steelmakers and specialized domestic producers with strong regional footprints. Market concentration remains moderate, with the top three firms holding approximately 25.8 percent of revenue and the top five reaching 32.4 percent. This structure suggests that while scale confers advantages, there is meaningful space for regional specialists to compete on service, lead times, and product specificity.
Nucor, headquartered in Charlotte, North Carolina, exemplifies the vertically integrated approach. As an electric arc furnace producer of domestic hollow structural sections and tested steel pipe—covering ASTM A500, A135/A795, and A53 specifications—Nucor has positioned itself around low-embodied carbon certification and domestic supply reliability. That positioning has translated into conspicuous pricing activity: in October 2025, the company announced a 50 USD per ton increase across tube steel, HSS, mechanical, and piping products, followed by a further 60 USD per ton increase implemented in February 2026. These moves signal not only cost pass-through but also a deliberate effort to protect margin in an environment where input costs and demand are both elevated.
ArcelorMittal, based in Luxembourg City, remains a global force in tubular products, producing high-strength structural steel pipe and welded pipes for infrastructure and energy applications. Its recent product development activity highlights the innovation dimension of competition: by May 2026, ArcelorMittal Nippon Steel India had commenced commercial production of EQ70 grade high-strength welded steel pipes with a 690 MPa yield at its Hazira mill, enabling weight savings in structural applications. Such advances illustrate how competitors are using grade differentiation and performance improvements to capture premium segments, rather than competing solely on volume.
Structural Steel Pipe Market
United States Steel Corporation, headquartered in Pittsburgh, continues to supply welded and structural steel pipe and tubing critical to construction and infrastructure programs. Meanwhile, California Steel Industries, based in Fontana, serves the western United States with ERW structural steel pipe and tubing for load-bearing and low-pressure applications. These regional specialists matter because they shape localized availability and lead time dynamics. In February 2026, structural tubing mills broadly extended lead times to 6–8 weeks amid rising pricing and demand—an industry-wide signal that procurement planning horizons must lengthen and inventory buffers may need recalibration.
The full report goes deeper into how these players—and the broader field—compete on pricing, product certification, lead time reliability, and sustainability credentials. It evaluates where vertical integration provides genuine insulation from input volatility and where it may create rigidity. It also examines how low-embodied carbon positioning is becoming a differentiator in bids where procurement teams are weighing total cost of ownership against decarbonization commitments.
Forces Reshaping Cost Structures and Pricing Power
Pricing in the structural steel pipe market is being influenced by a convergence of cost pressures, trade policy, and demand timing. Raw material and labor dynamics remain central. In the first quarter of 2026, steel scrap prices stayed firm to upward, with China pricing at 347.20 USD per metric ton and India at 397.20 USD per metric ton. These levels were supported by tight supply and higher freight costs, reinforcing the upward bias in producer input costs and constraining the ability of mills to absorb cost shocks without passing them downstream.
Trade policy has added another layer of complexity. Section 232 tariffs on steel imports were raised to 50 percent in June 2025 and affirmed in April 2026, applying directly to steel pipe and structural products. In parallel, Section 301 tariffs on steel pipe, tube, and structural shapes from excess-capacity countries continued to impact import costs as of May 2026. Together, these measures have altered the relative attractiveness of imported versus domestic supply, tightened available sourcing channels, and strengthened the pricing hand of domestic producers in certain markets.
The price environment has responded accordingly. Steel pipe and tube prices rose 12.5 percent year-over-year in spring 2026, with the producer price index for metals reaching 354.9 in March 2026. These movements matter for budgeting, bidding, and contract structuring. For buyers, they raise the stakes of contract timing, escalation clauses, and inventory strategy. For producers and distributors, they create opportunities to defend margins but also increase the reputational and operational risks associated with lead time reliability and service continuity.
The report provides a structured framework for interpreting these dynamics. It connects raw material indices, tariff timelines, and demand seasonality to practical forecasting tools that help organizations model price scenarios, evaluate make-versus-buy trade-offs, and design procurement contracts that share risk more intelligently. Rather than simply documenting that prices have risen, it explains the mechanisms behind the increases and the conditions under which they may ease or intensify.
What the Full Report Delivers: Operational Intelligence for 2026 and Beyond
This introduction provides the strategic framing; the complete report delivers the operational intelligence required to act on it. Designed for executives, category managers, supply chain planners, and investors, the study translates market data into decision-ready formats. Key content includes a detailed historical reconstruction from 2020 through 2025, a forward-looking forecast spanning 2026 to 2032, and scenario analyses that stress-test assumptions around input costs, tariffs, and demand cycles.
Readers will find a robust segmentation evaluation covering product types and application verticals, along with a regional assessment that connects local supply conditions to cross-border trade realities. The competitive section profiles major players and analyzes recent moves—including price actions, grade launches, and lead time shifts—that signal where market power is being exercised and where vulnerabilities are emerging. The regulatory and cost environment is examined not as background noise but as an integral input to procurement and investment decisions.
Structural Steel Market
Equally important, the report emphasizes practical application. It outlines how to interpret lead time extensions, how to evaluate the implications of tariff structures on total landed cost, and how to incorporate sustainability credentials into sourcing criteria without losing sight of cost and performance. It also provides the analytical scaffolding needed to anticipate where the market is likely to tighten or loosen over the forecast horizon, giving stakeholders a basis for proactive rather than reactive planning.
Why This Research Matters Now
The structural steel pipe market in 2026 is defined by strong but uneven growth, elevated input costs, shifting trade policy, and a competitive field in which both global scale and regional agility matter. Organizations that treat these conditions as isolated events risk mispricing risk and misaligning supply strategies. Those that integrate them into a coherent, data-backed view can make better decisions on contracting, inventory, capacity, and market entry.
The complete report is built to support that integration. It combines the macro trajectory—moving from 386.5 million USD in 2025 toward 489.1 million USD by 2032 at a 3.45 percent CAGR—with the granular, decision-level detail that turns numbers into strategy. For teams responsible for procurement, planning, or investment in structural steel pipe, the difference between reacting to price spikes and anticipating them can be material.
To access the full segmentation analysis, regional assessments, competitive profiles, and scenario-based forecasts, request the complete market research. The methodology, data tables, and actionable recommendations are structured to give your organization a clear line of sight from market intelligence to executive decision-making in 2026 and across the forecast period to 2032.
For detailed analysis of this topic, please visit the official page: Structural Steel Pipe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting ESWL Market Hits $381.96M in 2025, Projects 5.5% CAGR to $552.74M by 2032
By PW Consulting, 2026-09-16
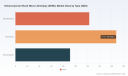
Strategic Horizons in Extracorporeal Shock Wave Lithotripsy: A 2026 Market Perspective
The global landscape for Extracorporeal Shock Wave Lithotripsy (ESWL) is entering a decisive phase of transformation. As healthcare systems worldwide balance cost containment with the demand for minimally invasive urological interventions, understanding the trajectory of this market is no longer optional for strategic planners—it is imperative. This article serves as an executive overview of our latest comprehensive market research, designed to equip stakeholders with the intelligence needed to navigate the forecast period from 2026 through 2032.
Our analysis indicates that the market is on a steady upward path. Following historical growth patterns observed between 2020 and 2025, where revenue climbed from approximately 294.62 Million USD to 381.96 Million USD, the momentum is expected to continue. The forecast period projects a compound annual growth rate (CAGR) of 5.5 percent. By 2032, the market volume is anticipated to reach significant maturity, driven by technological advancements and shifting clinical preferences. However, raw figures only tell part of the story. The real value lies in understanding the underlying dynamics that will dictate profitability, market share, and operational feasibility for providers and manufacturers alike.
Market Dynamics and Operational Realities
The ESWL sector does not operate in a vacuum. It is influenced by a complex interplay of regulatory frameworks, reimbursement structures, and capital expenditure constraints. Our report dives deep into these friction points to provide a realistic view of market entry and expansion opportunities.
Regulatory and Clearance Milestones
Recent regulatory activities highlight the pace of innovation and the hurdles remaining for new entrants. For instance, recent clearance events have validated new devices under specific federal classifications, signaling both opportunity and heightened scrutiny. The approval of specific lithotripters under Class II regulations demonstrates that while the pathway is established, the bar for clinical efficacy and safety documentation remains high. Companies aiming to launch new units must navigate these regulatory corridors with precision. Our research details the specific implications of these clearances for future product pipelines and competitive barriers.
Reimbursement and Economic Viability
Financial sustainability for ESWL procedures relies heavily on reimbursement codes. The economic environment for 2026 suggests varied payment structures depending on the care setting. National average Medicare payments differ significantly between ambulatory surgical centers and hospital outpatient departments. This disparity influences where providers choose to locate their services and how they structure their billing practices. Understanding the nuances of Current Procedural Terminology codes and their associated payment rates is critical for forecasting net revenue. Our report dissects these reimbursement landscapes to help stakeholders model accurate financial projections.
Capital Investment Considerations
The barrier to entry for ESWL technology remains substantial. Initial capital investment for systems varies widely, ranging from mobile units to stationary configurations. The cost differential between these options impacts hospital budgeting cycles and procurement strategies. Mobile units offer flexibility but may limit throughput, while stationary systems provide stability at a higher upfront cost. Strategic decision-makers must weigh these capital costs against expected utilization rates and maintenance expenses. We provide a granular breakdown of cost structures to assist in capital allocation decisions.
Technology Segmentation and Clinical Application
The market is segmented by technology type and clinical application, each presenting distinct growth vectors. While the overall market expands, specific technologies are gaining traction due to improved precision and reduced complications. Similarly, the prevalence of different stone types dictates where demand will concentrate.
Technology Evolution
Different shock wave generation technologies compete on efficacy, durability, and cost. The market includes electrohydraulic, piezoelectric, and electromagnetic systems. Each type carries different implications for maintenance, energy consumption, and patient outcomes. Our analysis evaluates the maturity and adoption rates of these technologies across different healthcare settings. We examine how technological shifts are influencing purchasing decisions among major healthcare providers.
Application Diversity
While kidney stones remain the primary driver of demand, other applications are contributing to market expansion. Ureteral stones, pancreatic stones, and salivary stones represent additional revenue streams that are often overlooked in broader analyses. The clinical protocols for these conditions vary, influencing the type of equipment required and the specialist involved. Our report maps the volume and growth potential across these applications, providing a clear picture of where niche opportunities exist.
The competitive landscape is moderately concentrated, with a few key players holding significant market share. This concentration suggests that while there is room for innovation, competitive pressure on pricing and service levels is intense. Our report provides a detailed competitive intelligence section that profiles the strategies of leading manufacturers.
Key Players and Strategic Moves
Several companies are defining the current market standards. German engineering firms have historically held strong positions, leveraging reputation for durability and precision. Simultaneously, manufacturers from emerging manufacturing hubs are increasing their presence through aggressive pricing and rapid innovation cycles.
-
Dornier MedTech: A longstanding participant known for establishing clinical benchmarks in shock wave technology. Their strategy focuses on maintaining high clinical efficacy standards.
-
Karl Storz GmbH & Co. KG: Integrates ESWL solutions within broader endoscopic and urological portfolios, offering bundled solutions that appeal to comprehensive care centers.
-
Siemens Healthineers: Leverages extensive imaging and diagnostic capabilities to enhance the precision of lithotripsy procedures, positioning technology as a integrated diagnostic-therapeutic solution.
-
Shenzhen Wikkon Precision Technologies Co., Ltd.: Represents the growing influence of manufacturers from the Asia-Pacific region. Recent activities indicate a push towards global regulatory approval and branding.
Extracorporeal Shock Wave Lithotripsy (ESWL) Market
Recent Developments and Market Shifts
Recent actions by key competitors signal shifting strategies. In mid-2025, Shenzhen Wikkon Precision Technologies Co., Ltd. achieved a significant regulatory milestone with FDA 510(k) clearance for their U200 Extracorporeal Shock Wave Lithotripter, specifically indicated for kidney stone treatment. This clearance under 21 CFR 876.5990 opens the US market to this specific device. Following this, in late 2025, the company launched a new brand identity and announced global expansion plans during a meeting of the Chinese Urological Association. These moves suggest a deliberate strategy to scale presence in Western markets while consolidating strength in home regions.
However, competition is not limited to these profiled entities. The market concentration metrics indicate that the top three players hold over half of the market revenue, and the top five control approximately 65 percent. This structure implies that market entry for new players requires significant differentiation, either through cost leadership or proprietary technology. Our report analyzes the strategic postures of these leaders to identify potential vulnerabilities and partnership opportunities.
Strategic Imperatives for 2026 and Beyond
As we look toward the forecast period, several key strategic imperatives emerge for stakeholders involved in the ESWL market. Success will depend on the ability to align technology procurement with reimbursement realities, manage capital expenditures efficiently, and adapt to a competitive landscape that is both concentrated and dynamic.
Optimizing Procurement and Deployment
Healthcare providers must look beyond the sticker price of ESWL systems. The total cost of ownership, including maintenance, disposable components, and energy consumption, must be factored into procurement decisions. With capital costs ranging significantly based on system type, facilities need to model their expected patient volume to justify the investment. Our research provides frameworks for calculating return on investment based on procedure volumes and reimbursement rates specific to different care settings.
Navigating Regulatory Pathways
For manufacturers and distributors, the regulatory environment remains a critical gatekeeper. Recent clearances demonstrate that compliance is achievable, but the process requires robust clinical data. Companies planning product launches must anticipate regulatory timelines and prepare corresponding quality management systems. The report outlines the specific regulatory requirements and recent precedents that will shape future approval processes.
Capitalizing on Regional Variances
Market growth is not uniform across geographies. Different regions exhibit varying levels of adoption based on healthcare infrastructure, reimbursement policies, and disease prevalence. While some regions show higher immediate revenue potential, others may offer faster growth rates due to developing healthcare access. Strategic expansion plans should be tailored to these regional characteristics rather than applying a one-size-fits-all approach. Our report includes detailed regional analysis to guide market entry and resource allocation.
Conclusion
The Extracorporeal Shock Wave Lithotripsy market presents a landscape of steady growth tempered by complex operational challenges. With a projected CAGR of 5.5 percent leading into the next decade, the opportunity for value creation is substantial. However, realizing this potential requires more than superficial market knowledge. It demands a deep understanding of reimbursement mechanics, capital constraints, regulatory pathways, and competitive strategies.
This article has provided a high-level overview of the forces shaping the ESWL market. Yet, the true depth of intelligence lies in the data points, specific segmentation values, and detailed company profiles contained within our full report. For executives and investors who need to make precise decisions regarding market entry, product development, or investment allocation, the granular details are essential. We invite you to access the full market research report to uncover the specific data driving these trends. The complete analysis offers the actionable intelligence required to turn market insight into strategic advantage.
Extracorporeal Shock Wave Therapy Device Market
For detailed analysis of this topic, please visit the official page: Extracorporeal Shock Wave Lithotripsy (ESWL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
在數位經營的環節中,社群貼文的回應熱度與頁面上的正面回饋,往往在無形中影響著瀏覽者的第一直覺。當潛在顧客造訪時,若呈現的是極少互動與空白紀錄,容易讓人有所猶豫;相對地,熱絡的討論聲量與良好的評價積累,則能 自然地 為品牌鋪陳初期的信任基礎。為了在經營初期更有效率地建立視覺熱度與互動氣氛,不少品牌與創作者會尋求外部資源的輔助,而 FansKing 正是許多人在規劃社群聲量與互動維護時會參考的管道之一。
如果您對FB貼文加讚有興趣,可以參考這篇: 最新Facebook買讚數推薦懶人包

FB買留言與五星評論有用嗎?會有被鎖的風險嗎?
1. FB買留言與五星評論有用嗎?
留言數與星級評價是Facebook粉專最重要的社群認證之一。當你發布一則產品貼文或活動訊息時,若留言區空無一人,潛在客戶可能會覺得「這則貼文好像沒什麼人在討論」,進而降低互動與購買意願。在這種情況下,適度購買留言與五星評論可以快速提升貼文的討論熱度與粉專的評價星數,營造出品牌受歡迎、受信賴的形象,增加客戶的信任度與停留時間。FansKing提供的FB買留言與五星評論服務,就是協助品牌在經營初期快速建立基礎社群認證的一種方式。
2. 留言與評論會影響Facebook的演算法表現
Facebook的演算法會將「留言數」「互動率」「貼文停留時間」列為推薦與否的重要指標。當你的貼文留言數較多時,系統會判斷這是一則「值得被更多人看到」的內容,進而提高貼文的自然觸及率。同樣地,粉絲專頁的五星評論也會影響專頁在搜尋結果與推薦版位中的曝光機會。也就是說,留言與評論不只是給訪客看的數字,更可能實際影響Facebook的推薦機制。透過FansKing購買留言與五星評論,可以在短時間內拉高貼文的初始互動數與粉專評價,讓演算法更容易注意到你的內容。
3. FB買留言與五星評論會有被鎖帳號的風險嗎?
購買留言與五星評論本身並不會直接導致帳號被鎖,真正可能導致帳號被限制的原因,通常是因為貼文或評論內容違反平台規範,例如涉及暴力、色情、詐騙或侵權內容。然而,購買留言與評論的關鍵在於「品質」與「來源」。Facebook在其社群守則中明令禁止虛假互動行為,其系統可標記重複文本、複製貼上的發布時機,以及低可信度帳號在短時間內集中發文的行為[reference:0]。因此,選擇像FansKing這類提供高品質帳號與漸進式交付的專業平台,才能在提升留言數與評價的同時,降低不必要的風險。
如果您對推特貼文加讚有興趣,可以參考這篇: 最新Twitter買讚數推薦懶人包

FB買留言會被發現嗎?
1. 如何有技巧地購買留言與評論
這點請放心,一般訪客只能看到貼文的留言數與評論區的星級評價,並不會知道這些留言的具體來源。因此,你可以適度增加留言數與評論數來提升貼文的討論熱度與粉專的評價,而不必擔心被訪客發現。關鍵在於選擇漸進式的增長方式,避免短時間內暴增過多留言,這樣才能維持自然成長的外觀。FansKing的留言服務通常會依照貼文發布時間分批次進入,讓留言的出現節奏看起來更自然。
2. 選擇高品質的留言與評論平台
許多廠商為了吸引顧客,往往會提供低價劣質的留言與評論,然而買了這種低端留言對你的粉專可能帶來更大的負面影響,包括重複話術、空白帳號資料、與貼文主題無關的內容,這些都會損害貼文的相關性與粉專的可信度。因此,選擇穩定可靠的高品質留言與評論平台非常重要,FansKing這類專注於社群增長的服務商,通常會提供多樣化留言內容與售後保固,讓客戶在購買留言與評論時更有保障。
如果您對IG貼文加讚有興趣,可以參考這篇: 最新Instagram買讚數推薦懶人包

FB買留言與五星評論對品牌的優缺點大整理
1. 提升品牌網路知名度與粉專信任感
擁有較高的留言數與五星評價可以為你帶來許多好處,例如增加品牌或個人的知名度,提高粉專的社群價值和影響力,還能增加訪客對你品牌或商品的信任度和購買意願。此外,當貼文留言區較熱絡時,訪客更容易產生「從眾效應」,願意停留更久、留言互動,甚至分享貼文給朋友。五星評論更能直接影響潛在客戶的購買決策,因為許多人在購買產品或服務前,會先參考其他人的評價。透過FansKing快速建立粉專的基礎留言數與五星評價,就有更多機會讓真實訪客注意到你的品牌。
2. 重點還是需要用心經營內容
短期內適當的購買留言與評論可以達到有效曝光,但如果長期依賴購買留言而非優質內容來吸引受眾,最終仍會面臨互動流失的問題。因此,建議將FB買留言與五星評論視為「啟動助推器」,搭配穩定的內容經營策略,才能真正留住粉絲。貼文內容建議兼顧價值資訊與互動引導,不要全部都是推銷訊息,大部分內容應為產業知識、產品實測、趣味問答等,少量穿插品牌活動與促銷訊息,這樣才能提升訪客的留言意願與粉專留存率。FansKing的留言與評論服務可以幫助你度過冷啟動期,但後續仍要靠內容實力留住粉絲。
如果您對抖音影片加讚有興趣,可以參考這篇: 最新Tiktok買讚數推薦懶人包

自然提升FB留言與評論技巧
除了購買留言與五星評論之外,以下幾個自然提升互動的技巧可以幫助你長期經營粉專:
- 設計互動引導型貼文 :在貼文結尾加入開放式問句,例如「大家對這個功能有什麼想法?」或「你選A還是B?」,能有效引導訪客留言參與討論。
- 即時回覆留言 :在貼文發布後的30分鐘內回覆留言,能有效維持貼文的自然觸及率,也能鼓勵更多訪客加入討論。
- 固定發文頻率 :建議每週發布3至5次內容,養成粉絲的閱讀與互動習慣,避免粉專長時間沒有新內容而失去活躍度。
- 舉辦留言抽獎或票選活動 :透過抽獎或票選機制,直接鼓勵粉絲在貼文下方留言,不僅能增加留言數,也能提升貼文的自然觸及。
- 主動邀請忠實顧客留下五星評論 :在交易完成後,透過私訊或電子郵件邀請滿意的顧客到粉專留下五星評價,累積真實的正面口碑。
如果您對YT影片加讚有興趣,可以參考這篇: 最新Youtube買讚數推薦懶人包

FB買留言與五星評論平台推薦:FansKing
在眾多Facebook留言與評論購買平台中,FansKing是專注於社群媒體增長的服務商之一,提供FB貼文留言、粉專五星評論、社群粉絲、貼文按讚等多種方案。對於想快速提升貼文互動與粉專評價的品牌與創作者來說,FansKing是值得列入考慮的選擇。在選擇購買留言與評論的服務時,建議注意以下幾點:
- 是否要求提供帳號密碼 :正規的留言與評論服務只需要你的貼文連結或粉專網址,不需要你的帳號密碼或驗證碼。FansKing這類專業平台通常只會要求貼文或粉專的公開連結。
- 是否提供多樣化留言內容 :優質的平台會提供多樣化、符合貼文主題的留言內容,而非大量重複的相同文字。FansKing的留言服務能依照貼文主題調整留言風格,讓留言區看起來像真實討論。
- 是否採用漸進式交付 :好的服務會以自然的速度逐步增加留言與評論,避免短時間內暴增引起平台注意。FansKing的交付方式通常較為平穩自然,符合Facebook的互動節奏。
選擇留言與評論購買平台時,務必挑選口碑良好、只做高品質社群提升服務的專業網站,才能以合理的價格獲得真正有價值的社群認證。FansKing在社群增粉與互動提升領域累積了不少客戶評價,若你重視留言品質與售後保固,可以將FansKing納入比較名單。

結語
Facebook粉專的留言數與五星評價是建立品牌信任感的重要基石,互動的多寡直接影響訪客的停留意願、信任度與平台的推薦機會。適度地透過購買留言與五星評論來提升粉專的初始互動數字,可以幫助你更快突破冷啟動階段,讓粉專看起來更熱絡、更值得信賴。但請記住,買留言只是加速器,真正的長期增長仍然需要依靠優質內容和持續經營。 選擇像 FansKing 這樣的高品質加粉 Line 平台 ,搭配規律的內容發布策略與互動設計,才能在Facebook粉專的經營上取得最佳效果。
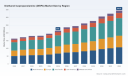
Unlocking Growth Trajectories in the Diethanol Isopropanolamine Market: A Strategic Imperative for 2026
The global chemical landscape is undergoing a quiet but decisive transformation, and at the center of this shift lies Diethanol Isopropanolamine, commonly known as DEIPA. Once confined to niche industrial applications, DEIPA has evolved into a critical enabler across construction chemistry, advanced materials, and precision manufacturing. As organizations navigate an era defined by supply chain recalibration, regulatory tightening, and demand concentration in high-value sectors, understanding the DEIPA market is no longer optional. It is a strategic necessity. Our latest comprehensive market study delivers exactly that clarity, providing enterprise leaders with the analytical rigor required to make informed capital allocation, sourcing, and expansion decisions throughout the forecast window.
The narrative arc of this market is compelling. Drawing from historical data spanning 2020 through 2025, the industry has demonstrated consistent expansion, culminating in a robust baseline valuation that sets the stage for an accelerated growth trajectory. The report projects a compound annual growth rate of 6.98 percent across the 2026 to 2032 period, pushing the market toward a multi-hundred-million-dollar valuation by the end of the forecast horizon. These macro indicators are not merely statistical artifacts. They reflect underlying structural shifts in how industrial chemicals are sourced, formulated, and deployed across increasingly specialized end-use environments. For corporate strategists, procurement directors, and market entry teams, this growth vector signals both opportunity and complexity. The challenge lies in translating broad market momentum into actionable, segmented intelligence that aligns with organizational capability and risk tolerance.
This is precisely where executive decision-makers encounter friction. Aggregate market size and headline growth rates offer direction, but they rarely provide the granularity required to model capacity expansion, pricing strategy, or regional prioritization. Our research framework is designed to bridge that gap. By dissecting demand drivers, supply chain dynamics, regulatory pressure points, and competitive positioning, the study equips stakeholders with a multidimensional view of where value is being created, where bottlenecks are emerging, and how incumbents and newcomers are positioning themselves for the next cycle. The objective is not to overwhelm with volume, but to deliver precision. Every analytical layer serves a practical purpose: reducing uncertainty, sharpening scenario planning, and enabling faster, more confident execution.
Diethanol Isopropanolamine (DEIPA) Market
Decoding the Structural Architecture of DEIPA Demand
DEIPA's growth story is fundamentally tied to its functional versatility. As a specialized chemical intermediate and performance additive, it serves applications where consistency, purity, and formulation compatibility are non-negotiable. The market's demand architecture reflects this reality, with certain application verticals commanding disproportionate share due to their sensitivity to chemical performance and their growth momentum in high-tech and infrastructure sectors. Understanding which verticals are expanding, which are consolidating, and how feedstock volatility influences pricing behavior is essential for any organization operating in or adjacent to this space.
From a supply-side perspective, the DEIPA ecosystem is characterized by a concentrated but strategically active manufacturing base. The report examines how leading producers are navigating raw material fluctuations, particularly around isopropanolamine and diethanolamine, whose pricing can swing sharply in response to global market instability. These input cost dynamics are not abstract concerns. They directly impact margin structures, inventory strategies, and long-term contract positioning. Organizations that integrate feedstock risk modeling into their procurement and production planning gain a measurable advantage, especially when competing in price-sensitive or specification-driven segments.
Equally critical is the role of product differentiation. Within the DEIPA market, performance tiers and purity specifications increasingly dictate commercial outcomes. The study maps how different product configurations align with specific industrial requirements, revealing where premium positioning can sustain pricing power and where volume-driven strategies may be necessary to capture scale. This segmentation lens allows companies to avoid the common trap of treating DEIPA as a homogeneous commodity, and instead approach it as a portfolio of distinct value propositions with varying margin profiles, customer retention characteristics, and entry barriers.
Navigating Regulatory Friction and Cost Dynamics
Growth in the DEIPA market does not occur in a vacuum. Environmental and compliance frameworks are reshaping production economics, particularly in mature markets where regulatory scrutiny has intensified. The research highlights a clear pattern: stringent environmental requirements in North America and Europe are elevating production costs for DEIPA manufacturers, forcing a strategic recalibration of operating models. Compliance is no longer a peripheral consideration. It is a core determinant of competitive positioning, capacity utilization, and regional sourcing strategy.
The operational reality on the ground is stark. A significant portion of global producers are encountering environmental compliance hurdles that affect throughput, capital planning, and time-to-market for new formulations. Nearly half of surveyed manufacturers report restrictions related to volatile organic compounds as a meaningful restraint, while more than half cite broader compliance challenges as direct pressure points on their operational footprint. These figures underscore a market where regulatory agility is becoming a differentiator. Companies that proactively invest in emission control, process optimization, and documentation readiness are better positioned to sustain production continuity, while those that treat compliance as reactive overhead risk margin erosion and supply disruption.
Worldwide N-Methyl Diethanolamine (MDEA) Market
Raw material volatility further compounds this environment. Because DEIPA production depends on precursor chemicals that are exposed to global pricing instability, manufacturers must balance cost pass-through mechanisms with customer retention strategies. The report explores how leading firms are structuring hedging approaches, renegotiating supply agreements, and adjusting formulation strategies to preserve competitiveness without sacrificing compliance standards. For procurement and commercial teams, these insights are vital. They reveal where pricing negotiations are likely to face resistance, where long-term contracts can create structural advantage, and where regional regulatory divergence may open arbitrage opportunities for organizations with multilateral sourcing capabilities.
Competitive Positioning and the Landscape of Strategic Operators
The DEIPA market is not dominated by a single monolithic player. Instead, it features a coalition of specialized producers, regional manufacturers, and distribution networks that collectively shape supply availability, technical service expectations, and market access. The research profiles a set of core companies whose operational footprint and strategic focus provide a clear window into how the market is being contested. These include established producers such as Nanjing Hongbaoli Group Co., Ltd. and Shandong Inniolamine New Material, which anchor significant production capacity around high-purity DEIPA grades for cement grinding aids and concrete admixtures. Their positioning reflects a broader trend in Asian manufacturing ecosystems, where scale, export orientation, and specification refinement are converging to support both domestic infrastructure demand and international supply channels.
India's chemical manufacturing base also features prominently, with organizations like Viswaat Chemicals Limited and Amines & Plasticizers Limited operating as influential contributors to the DEIPA supply chain. Their focus on construction chemicals and cement applications aligns with the region's ongoing infrastructure expansion and the increasing adoption of chemical admixtures to improve performance efficiency. Meanwhile, distribution and trading specialists such as Bisley International LLC play a critical intermediary role, ensuring that industrial and construction end-users can access DEIPA with reduced friction across geographies and specification requirements. This diversified competitive architecture means that market access is rarely about securing a single supplier relationship. It is about understanding how manufacturers, formulators, and distributors interact to create reliability, technical support, and pricing stability.
The report also examines market concentration as a structural indicator of competitive intensity. With a CR3 near 24.6 percent and CR5 at approximately 26.2 percent, the market displays a moderately fragmented profile. This concentration pattern suggests that while leading players hold meaningful influence, there remains substantial room for regional specialists, product-focused innovators, and service-oriented distributors to capture share through differentiation rather than scale alone. For companies evaluating partnerships, acquisitions, or greenfield capacity, this landscape offers multiple entry and expansion pathways, each with distinct risk-reward profiles depending on target segment, geographic exposure, and technical capability requirements.
Translating Market Intelligence into 2026 Execution
What separates useful market research from strategically actionable intelligence is relevance to decision cycles. Our DEIPA study is built around that principle. Rather than stopping at descriptive analysis, the report integrates practical frameworks that help organizations align market signals with internal planning processes. This includes scenario-based forecasting approaches that account for feedstock volatility, regulatory escalation, and demand concentration shifts. It also encompasses supplier evaluation criteria, regional cost-structure comparisons, and application-level demand sensitivity mapping that supports more precise commercial targeting.
For product and R&D teams, the research provides a structured view of specification trends and performance expectations across end-use environments. This enables formulation teams to anticipate where purity thresholds, compatibility requirements, or additive performance benchmarks are moving, reducing the lag between market demand and product readiness. For manufacturing and operations leaders, the study highlights where process efficiency, compliance readiness, and feedstock procurement strategy intersect, offering a basis for capital prioritization and capacity optimization. For commercial and go-to-market teams, the segmentation and competitive analyses clarify where pricing stability is most achievable, where technical service differentiation can protect share, and where geographic expansion may yield disproportionate returns.
The report's design reflects a commitment to operational utility. It organizes complex market dynamics into decision-ready components, allowing executive teams to extract relevant insights without navigating irrelevant detail. Whether the objective is to reassess sourcing strategy, evaluate expansion into adjacent application areas, benchmark competitive positioning, or stress-test margin assumptions under regulatory and raw material pressure, the study provides a coherent foundation for those conversations. In a market where misreading a single variable can compound into inventory imbalance, pricing misalignment, or missed entry windows, that coherence has direct financial and strategic value.
The Strategic Edge in an Accelerating Market
DEIPA is no longer a peripheral chemical story. It is a market where demand growth, regulatory pressure, raw material dynamics, and competitive differentiation intersect in ways that reward informed, anticipatory decision-making. The projected growth trajectory through 2032 signals that the window for strategic positioning is open, but it will not remain frictionless. Companies that treat DEIPA as a static procurement line item risk falling behind organizations that approach it as a strategic capability area, integrating market intelligence into sourcing, product development, compliance planning, and commercial execution.
Our full market study goes deeper into every dimension that matters for 2026 planning and beyond. It unpacks regional demand architectures, application-level growth drivers, competitive movement patterns, and regulatory impact pathways with the level of detail required for credible strategic action. The executive summary provided here is intended to demonstrate analytical depth and establish confidence in the methodology, while preserving the precise segmentation data, detailed company assessments, and scenario modeling frameworks for the complete report. For decision-makers who need more than directional insight, accessing the full study is the logical next step. The market is moving, and the organizations that move with it most effectively will be those that invest in intelligence before they invest in execution.
For detailed analysis of this topic, please visit the official page: Diethanol Isopropanolamine (DEIPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com